Florida Real Estate Is Bucking the National Trend. Are We Paying Attention?
Oct 26, 2026
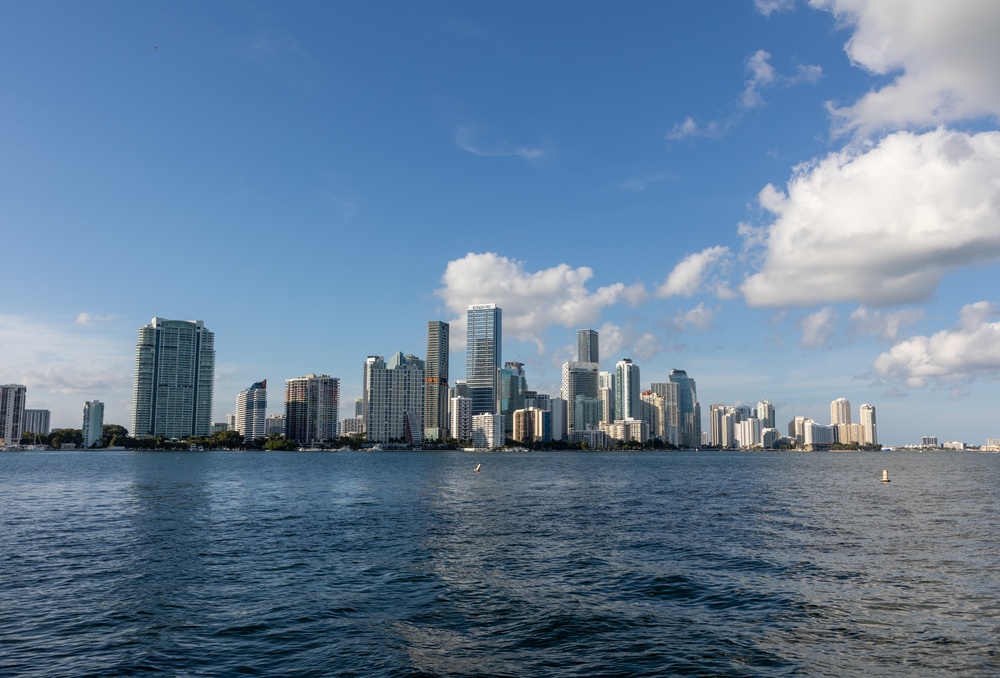
Miami waterfront. Photo: Patrick Bloodgood, U.S. Army Corps of Engineers / DVIDS. Public domain.
By Jeff Levine, Levine Coaching Company
Florida Real Estate Insights | October 26, 2026
National housing headlines can set the tone for an entire week of conversations. But before we repeat that story to a seller, a buyer, or our own team, we need to ask a better question: Does it describe the market where we actually do business?
Florida’s latest results give us a reason to look more closely. Several quarterly measures show resilience, even as national contract activity weakens. That deserves our attention. It also deserves careful interpretation.
Key takeaway: Florida is showing a different pattern in some measures, but the evidence does not support calling every segment a strong market. Think like a CEO: identify where the opportunity is, test your assumptions, and turn the numbers into a specific business decision.
What the Florida numbers show
Florida Realtors’ Q3 2026 single-family report covers July through September, compared with the same quarter in 2025:
- Closed sales: 65,904, up 0.2%.
- Median sale price: $420,000, up 2.4%.
- Median time to contract: 47 days, versus 52.
- Active inventory: 95,799 homes, down 9.8%.
- Supply: 4.4 months, versus 5.1.
- Sales of homes priced at $1 million or more: up 14.9%.
- Sales priced from $300,000 to $399,999: down 4.7%.
New pending single-family sales declined 2.5% for the quarter. Faster contracts among homes that sold should not be confused with growth in new contracts. Source: Florida Realtors’ Q3 single-family analysis.
For condos and townhouses, Q3 closings rose 3.1% to 22,664; the median price was $295,000, unchanged. September supply was 7.7 months, versus 4.4 for single-family homes. Source: Florida Realtors’ condo and townhouse analysis.
How Florida compares with the national trend
NAR reported that September 2026 pending home sales fell 7.3% from August and 11.3% from September 2025, with declines across all four regions. Pending sales measure signed contracts rather than completed closings. Source: NAR’s October 20 release.
These reports describe different periods and measures. Florida’s quarterly closed sales cannot be treated as a direct comparison with one month of national pending sales. They provide context, not proof that Florida has reversed the national contract trend.
So where is Florida bucking the story? The quarterly combination of relatively steady closings, tighter single-family inventory, and faster time to contract stands apart from a simple narrative of broad weakness. Yet Florida’s own decline in quarterly new pending sales is a reason to watch the pipeline carefully.
Levine Coaching perspective: Use the headline to start a conversation. Use the details to make the decision.
One state. Different business conditions.
A luxury single-family seller and a condominium owner may be operating in very different competitive environments. Even within the same city, the price range, community, property condition, and available competition can change the strategy.
That is why a statewide median cannot price a listing. It is also why stronger luxury transaction growth does not automatically create opportunity for an agent whose clients buy in another segment. Your business plan needs to reflect the people you serve and the inventory they can realistically purchase.
For condo conversations, examine the full ownership picture with the appropriate professionals. Association fees, insurance, reserves, and potential assessments belong alongside the asking price. Help clients identify the questions and documents they need before making a decision.
Turn market information into CEO decisions
1. Make pricing conversations specific. Bring recent comparable sales, competing listings, concessions, and local contract timelines. Agree on a review date and the evidence that would justify changing the strategy. Give sellers a process they can understand.
2. Audit the pipeline. Separate inquiries from qualified appointments, signed clients, pending contracts, and likely closings. Ask what must happen next for each opportunity to move forward. A busy calendar is useful only when the activity advances your business.
3. Match prospecting to your market. Review where your recent clients came from, which segments you know best, and where you can explain the local evidence clearly. Choose a focused message and a consistent follow-up process before adding another marketing expense.
4. Plan for the money you keep. Test how a slower closing or a lost transaction would affect your cash flow. Know your cost per closing and your operating commitments. Market resilience is encouraging; profitability still requires discipline.
Your next CEO decision
This week, choose one market segment you actively serve. Review its recent sales, competing inventory, contract activity, and time on market. Then compare that picture with your own appointments, signed clients, and expected closings.
Write down one decision you will make, who owns the next step, and when you will review the result. It might be a revised listing conversation, a more focused follow-up campaign, or a change to an expense. The purpose is to turn information into action you can measure.
Florida’s results are a reminder to pay attention to what is happening close to your business. Your next opportunity may become clearer when you stop repeating the broadest headline and start asking more precise questions.
Are you building your plan around the market you hear about—or the market you can actually measure?
Explore One-on-One Coaching or Profitable on Purpose: Think Like a CEO for help turning market information into a practical business plan.
Sources and reporting notes
Sources: Florida Realtors: Florida homes reach contract faster in Q3; Florida Realtors: Florida condo sales rise 3.1% in third quarter; NAR: Pending Home Sales Decreased 7.3% in September, released October 20, 2026.
Florida quarterly figures refer to Q3 2026 versus Q3 2025 unless stated otherwise. Supply figures identified as September are monthly readings. The national pending-sales figures cover September 2026. These are separate series, periods, and property groupings, not a matched statistical comparison. Median prices reflect the mix of homes sold. Commentary and business recommendations are Levine Coaching Company’s interpretation; local results vary.